


College sports is big business, especially from the standpoint of which schools are aligned with each other by conference. Schools leaving old conferences for new ones can mean a shift in the economics of the entire college sports ecosystem, particularly for football and basketball.
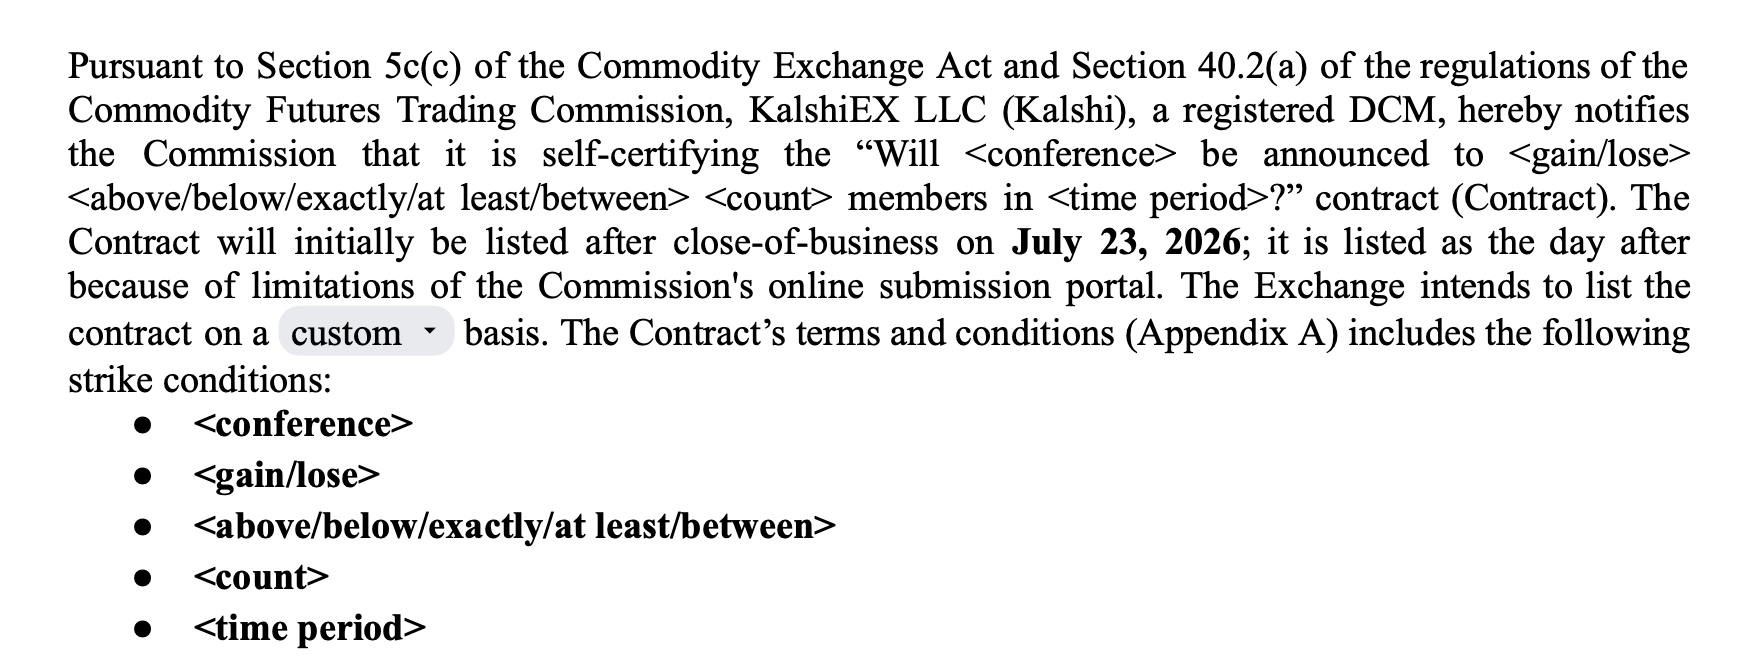
So, that Kalshi self-certified event contracts about potential realignment in college athletics should probably shock no one. These markets could have legitimate price-discovery and risk-management uses.
Here’s the self-certification:
And some examples for good measure:
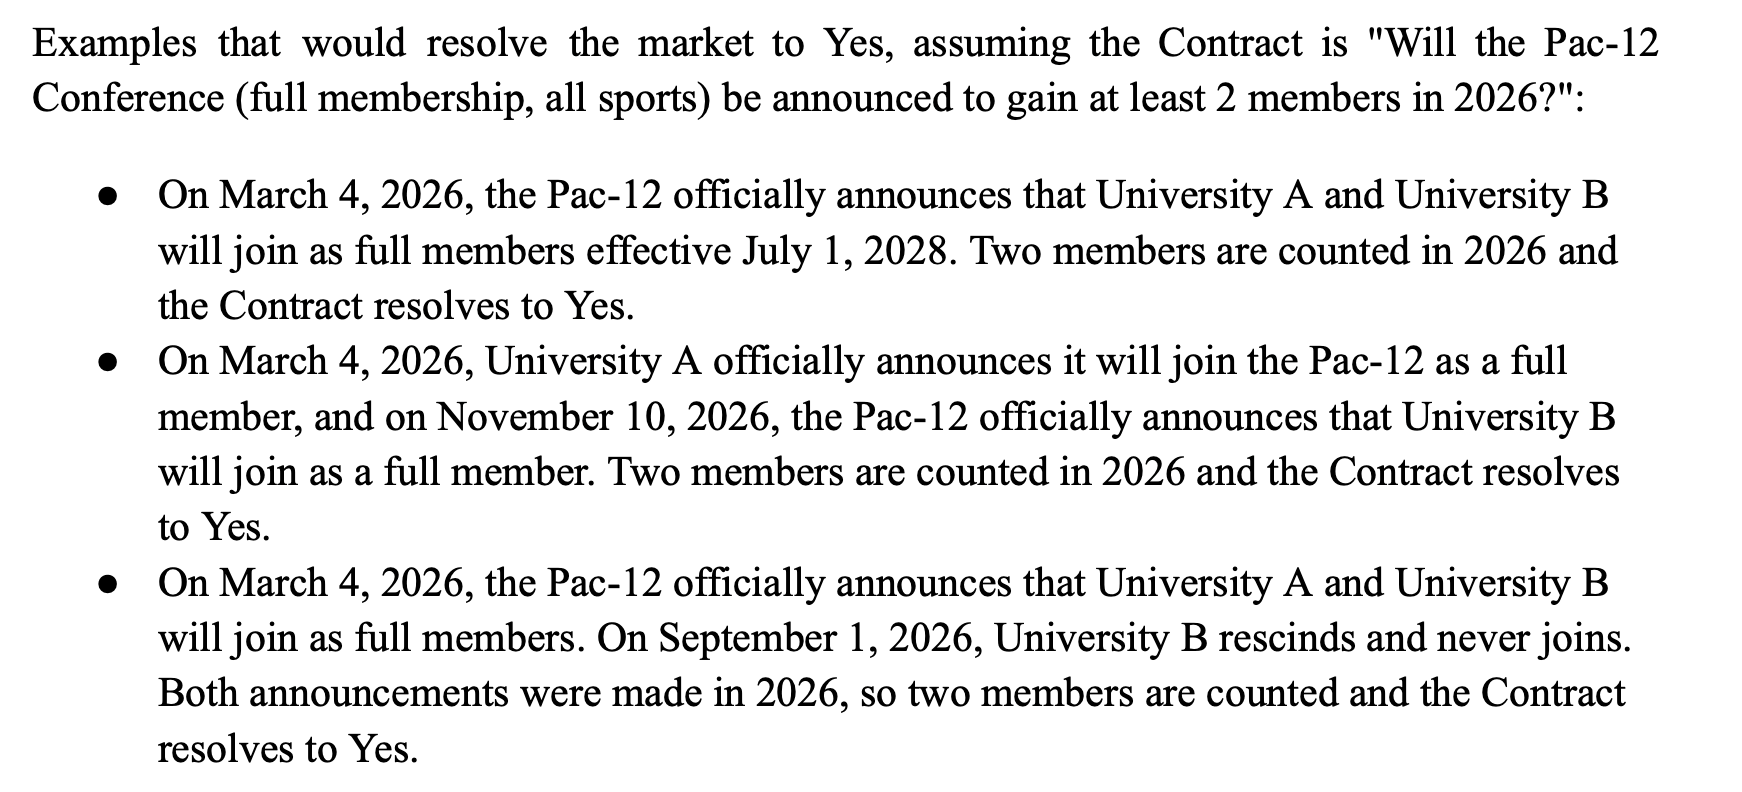
Kalshi has only self-certified the markets, so far, and has not actually listed them as of Thursday night, to be clear.
There are, no doubt, legitimate hedging (and price discovery) cases for markets on conference realignment. There are some problems with such markets, however:
The NCAA pretty much hates prediction markets with a passion, so I don’t see the point of further pissing them off by adding these types of markets, which are likely to be pretty niche. But, it’s probably hard to annoy the NCAA more than Kalshi et al. already have. So have at it, I guess.
More importantly, many of the parties with the clearest financial exposure to conference realignment — and therefore the most obvious potential hedging use cases — would be prohibited from trading.
Here’s the (pretty comprehensive!) list of prohibited individuals for this market type:
Employees, officers, commissioners, and governing board members of <conference (sport specific)> and of the league or association within which it competes, including NCAA governance and league office personnel.
Presidents, chancellors, provosts, trustees, regents, athletic directors, senior athletics administrators, general counsel, and chief financial officers of member institutions or teams, and of any institution or team in membership, expansion, or withdrawal discussions with the conference.
Owners, governors, executives, and employees of member teams and of candidate or expansion-bid teams, where <conference (sport specific)> is within a professional league.
Members of any conference expansion, realignment, or membership committee or working group.
Executives and employees of broadcast, streaming, or media-rights partners engaged in rights negotiations with the conference, its league or association, or any member or candidate institution or team.
Consultants, investment banks, law firms, private-equity or capital partners, and other advisors engaged on realignment, expansion, membership, media-rights, or related financing matters.
Government officials with approval or directive authority over a public institution’s conference affiliation, including members of state boards of regents or trustees.
Immediate family (parents, siblings, spouses) and household members of any of the above insiders.
Now, I can still imagine entities that might want to trade on these markets if the contracts are sufficiently specific. Things like:
Hotels, restaurants and local businesses near a school; Kalshi likes to highlight the utility of its markets to small businesses.
Investors and vendors holding debt or other exposure connected to an athletic department or local economy.
And probably others.
Does that mean these markets need to exist? I guess like a lot of things in prediction markets, that’s in the eye of the beholder. But I am guessing most of the trading in these markets would look more like gambling/speculation than hedging.
(One quick aside: Being able to identify all of the prohibited individuals that could be trading on these markets seems like a very heavy lift.)
Anyway, will we actually see these markets at Kalshi? Maybe, maybe not. But in a world where almost everything is an event that can be traded at a prediction market, don’t be shocked to see these markets come to life.
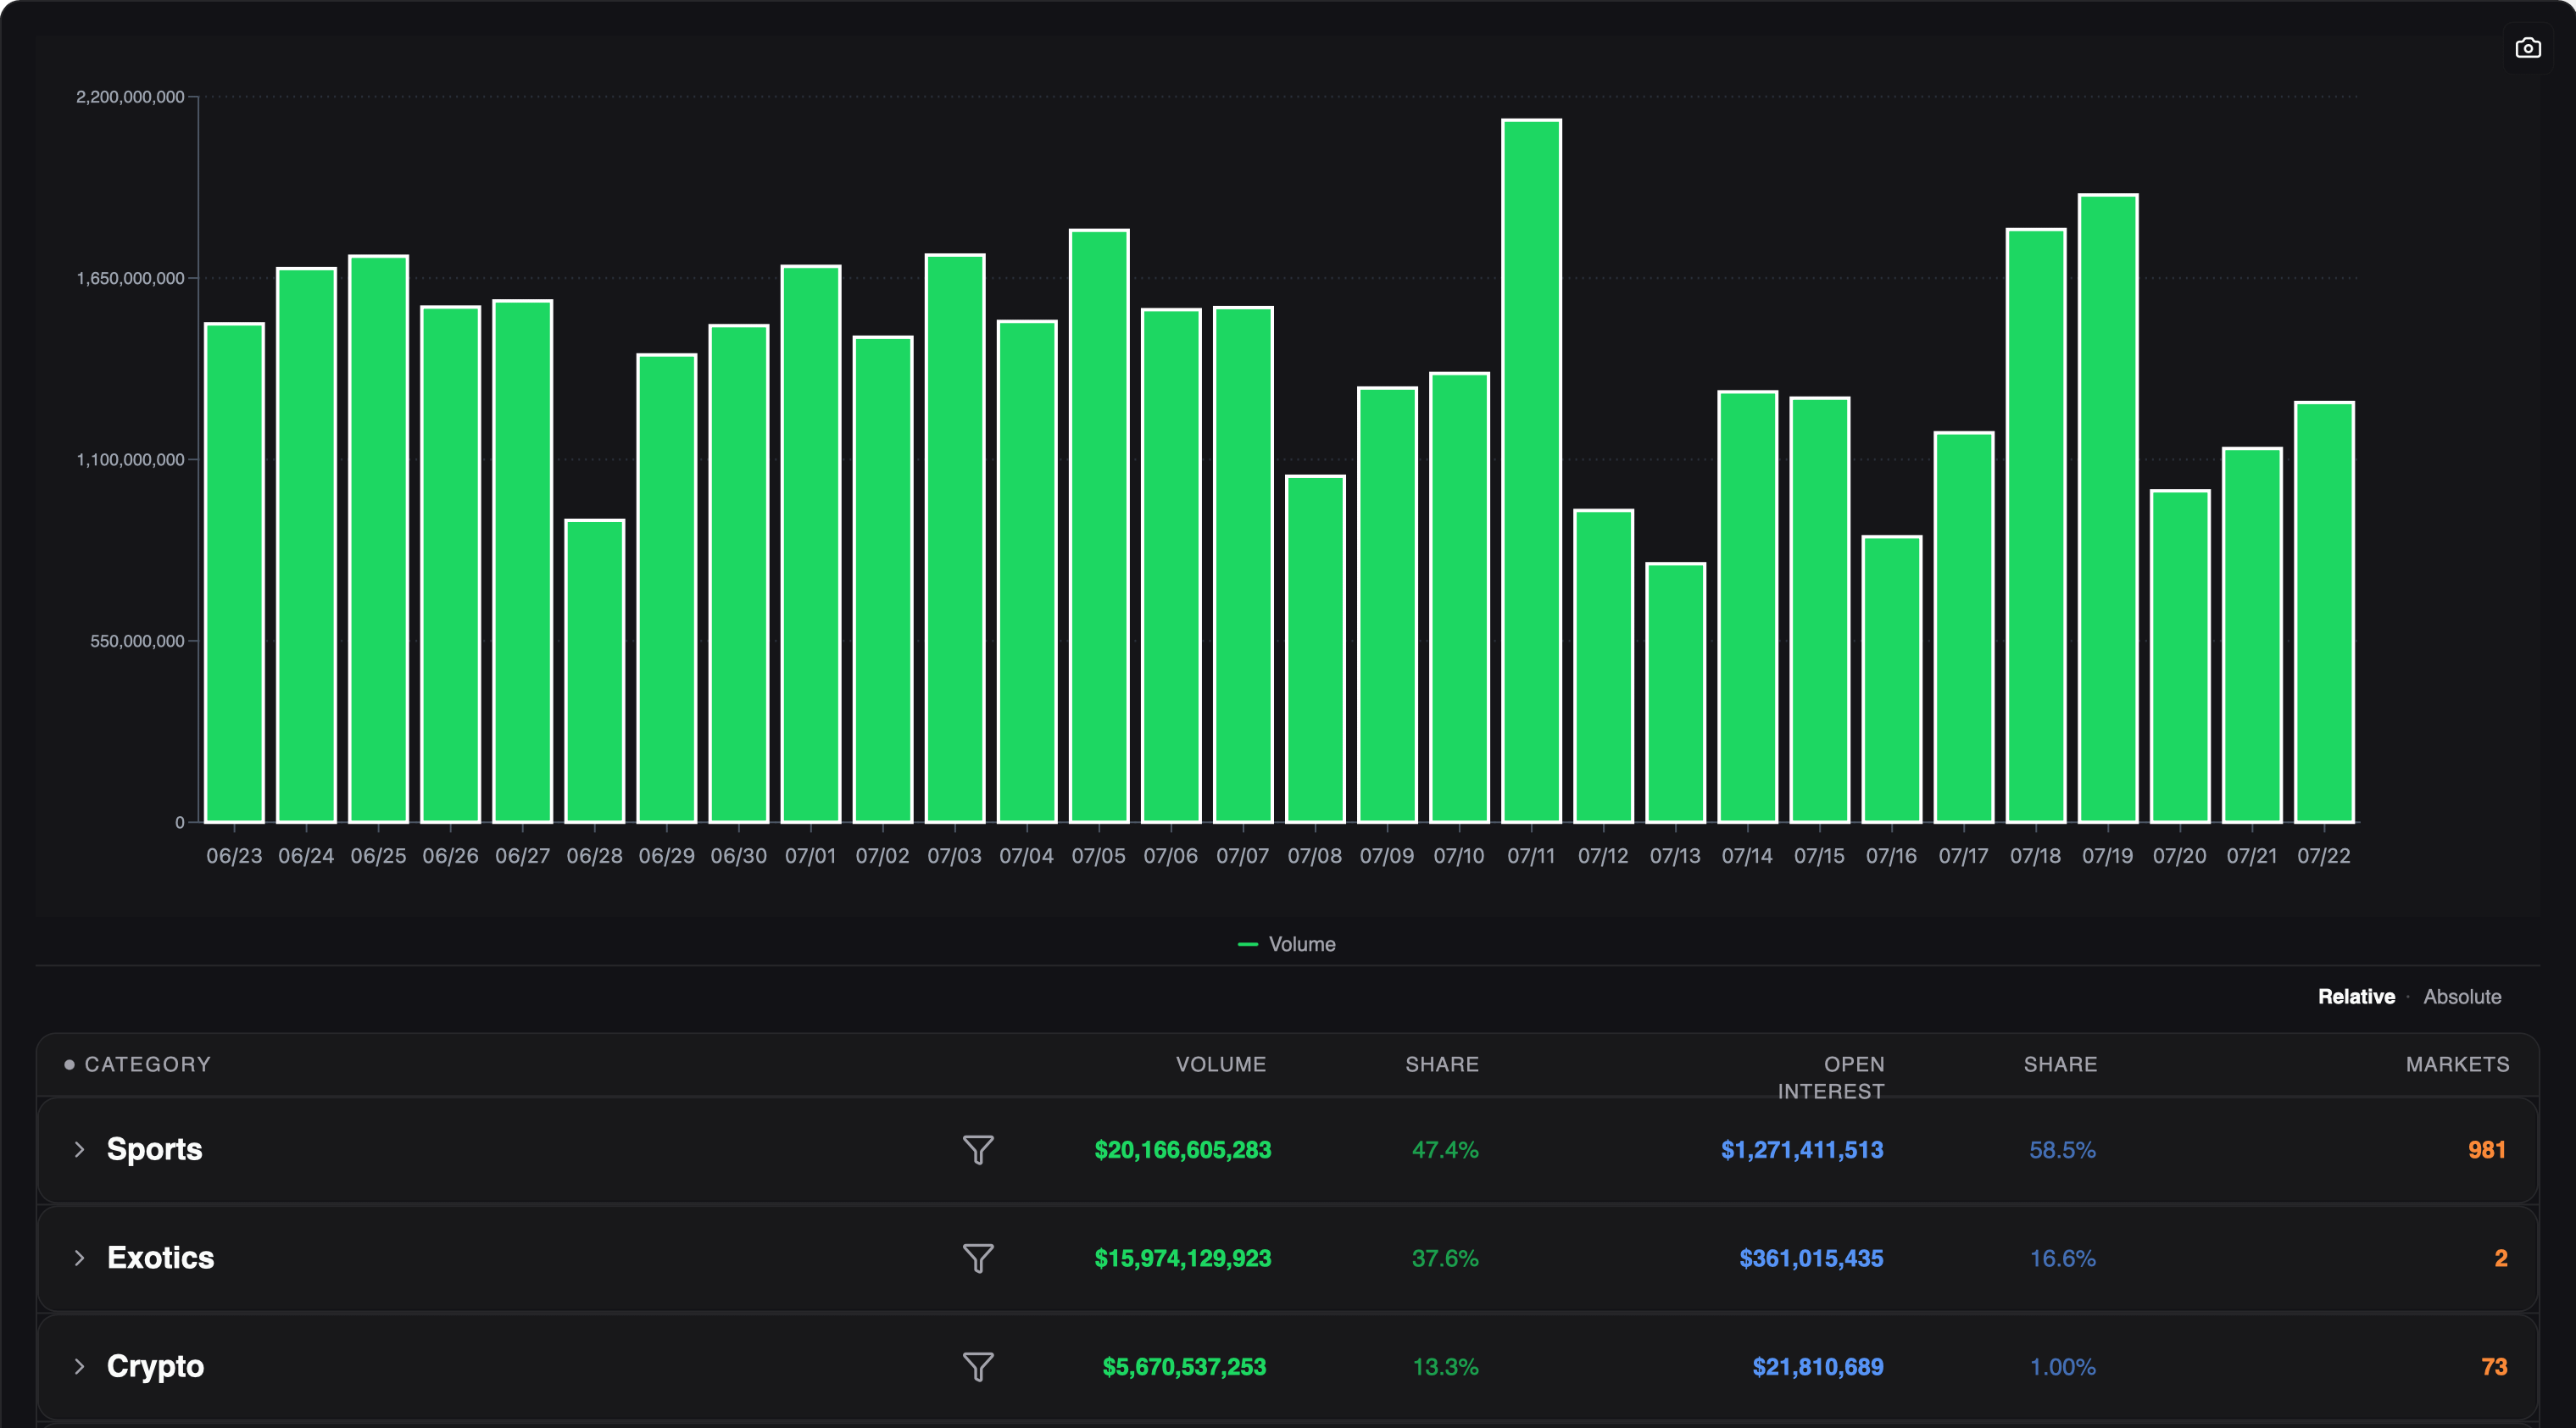
📊 The Ticker for Wednesday, July 22
Kalshi Volume: $1.27 billion
Sports + parlays: 81.2% of volume
Crypto markets: 17.1% of volume
Trend line from Ticker Tracker:
Prediction markets news roundup
🚨The important stuff
Betting on LeBron is big business:
From Cap Space… LeBron’s Decision 3.0 Is More Popular To Bet on Than Actual Basketball: “Before James has said a word publicly, Kalshi and Polymarket have processed a combined $203.4 million and counting on where he will play next season. That’s more money than either platform has ever taken on an NBA game or the College Football Playoff National Championship. On Monday evening it surpassed the market for the 2028 Democratic presidential nominee to become Kalshi’s 12th-largest market ever, despite only being open for six months.”
The hottest market on Kalshi is one the NBA doesn’t think should exist (The Washington Post/Yahoo): That is precisely the sort of market the NBA has told federal regulators should not exist.
“Markets relating to officiating, injuries, league disciplinary actions, player or team transactions, or fan actions should be prohibited,” Dan Spillane, the NBA’s executive vice president and assistant general counsel, wrote in an April letter to the Commodity Futures Trading Commission (CFTC), the federal agency that regulates derivatives, including prediction markets. “These markets are readily susceptible to manipulation and/or improper use of confidential information and have a negative effect on perceived game and league integrity.”
Netflix does prediction markets: Wrote a bit about it at The Closing Line; I was interviewed for the documentary:
Trailer:
 Netflix@netflixWhether it’s the World Cup or Taylor Swift’s wedding, tens of millions are betting on the outcomes of almost anything using prediction markets. Go inside the world of this legal but controversial form of gambling in INSTADOCS: THE PREDICTION GAMES. Premiering July 26.2:00 PM · Jul 23, 2026 · 2.04M Views147 Replies · 80 Reposts · 1.06K Likes
More from Netflix: Instadocs: The Prediction Games drops viewers into the red-hot center of betting fever, where millions are wagering they can predict the future and win big — fast. The installment features interviews with those who own the game, including Polymarket CEO Shayne Coplan and Kalshi CEO Tarek Mansour, as well as regulator Michael Selig, head of the Commodity Futures Trading Commission.
Prediction markets are a deceptively sophisticated idea, with roots far back in American history. But the allure of easy money can carry real risk: when bettors harass war reporters to publish fake news and hackers manufacture Spotify streams to win millions, has reality itself become a target for manipulation? Has the wisdom of crowds turned into mob rule?
And of course, there’s a healthy dose of controversy before it actually goes live:
 Marshall Cohen@MarshallCohenHmm...... this was filmed Sunday in Vegas, and shows people saying they used Kalshi and Polymarket to trade on the World Cup final. But prediction markets have been banned for Nevada-based users since March, per court order. Where and when did they do these trades?
 Netflix @netflixWhether it’s the World Cup or Taylor Swift’s wedding, tens of millions are betting on the outcomes of almost anything using prediction markets. Go inside the world of this legal but controversial form of gambling in INSTADOCS: THE PREDICTION GAMES. Premiering July 26.6:50 PM · Jul 23, 2026 · 5.48K Views5 Replies · 2 Reposts · 24 LikesMarshall Cohen@MarshallCohenUPDATE: I spoke to Kalshi and they said they want @netflix to take down this trailer because it's "misleading." They also said they looked into one of the featured trades (at 0:29) and determined that it was placed in 2025, before the court order in Nevada.7:16 PM · Jul 23, 2026 · 41.9K Views6 Replies · 7 Reposts · 63 Likes
Prediction Market Ads Are Out of Control (City Journal): “Americans are betting billions on prediction markets, staking money on everything from elections to album sales to football games. Legally speaking, though, they aren’t betting at all. Prediction markets are, according to them and to federal regulators, technically investment platforms, and the event contracts they offer are a type of financial derivative. Despite their status as legitimate financial platforms, prediction markets have engaged in marketing tactics that would make even a casino blush.”
🔍 It seems like everyone is pretty negative on advertising for sports betting and prediction markets. While there are at least some standards in gambling, there clearly could be more guardrails for PMs.


⚖️ Legal and regulatory news
Interesting context to a recent facial recognition bill that would impact prediction markets and sportsbooks:
 Jessica Welman@jesswelmanAs recently as yesterday, representatives from Kalshi have presented the absence of sportsbooks supporting this legislation as indifference to protecting minors, but this element is certainly another explanation of why they don't to be a part of this bill.
 Daniel Wallach @WALLACHLEGALGreat catch by @jesswelman. A federal bill deceptively titled "Facial Recognition to Protect Children Act" amends the Special Rule to make it easier for the CFTC to approve "gaming" contracts. It's co-sponsored by 5 Dems from sports betting states such as NY, NJ, MI & FL (+ CA).3:48 PM · Jul 23, 2026 · 1.75K Views3 Reposts · 6 Likes
How Should Prediction Markets Like Kalshi and Polymarket Be Regulated? (Bloomberg, video): “In this video, we explain how prediction markets work, why states and the Commodity Futures Trading Commission disagree over who has authority to regulate them, how courts have responded to the growing number of lawsuits, and why the answers could reshape the future of sports betting, event contracts, and prediction markets in the US.”


📣 Industry news
Kalshi Considers New Instrument for Copper Bets After AI Buildout Boosts Demand (Bloomberg): “We’re strongly considering” copper and palladium “as the next offerings after the precious metals contracts,” Chief Risk Officer Udesh Jha said in an interview. “Copper has a very strong story correlated with what’s happening in the AI and computing marketplace, in addition to the natural uses of copper over these years.”
The Economics of Compute (Kalshi Research): Compute prices have been supported by supply constraints and demand pressures that our markets are expecting to ease over the coming months. Risks persist, however, in potential grid interconnection delays, prolonged geopolitical conflict, and a shifting legislative landscape around data center construction.
Compute is, in the words of Nvidia’s CEO Jensen Huang, a “new natural resource.” Once merely a verb, the word has settled into common use as a noun – a shift that mirrors its own transformation from a back-office IT line item into the central strategic bottleneck dictating AI development, corporate capex and national industrial policy.
Given the surging equity valuations of companies tied to the industry – Nvidia, Amazon, SK Hynix – the question of most interest is not whether compute is currently scarce – it is – but whether that scarcity is structural or a supply-demand mismatch that is moving toward resolution. Kalshi’s markets, which decompose the compute supply chain into individual, tradable risk factors, give a cleaner read on this than equities or futures, where these dynamics are hard to disentangle.
📖 Everything else you should know/read
FIFA, global advisory body clash over potential betting irregularities at World Cup (The Athletic): American cryptocurrency-based prediction market Polymarket receiving $4.8 million (£3.6m) on markets for Spain not to defeat Cape Verde in their group-stage game, which ended in a goalless draw…
The findings, sources say, also detailed how Polymarket opened a market on July 2 asking, “Will Folarin Balogun play against Belgium?” That was opened on the same day the U.S. forward was shown a red card against Bosnia and Herzegovina in the last-32 stage.
We need prediction markets on this:
 Variety@Variety‘The Spell Off Live!’ Competition Game Show Sets Premiere Date on YouTubevariety.com‘The Spell Off Live!’ Competition Game Show Sets Premiere Date on YouTube2:00 PM · Jul 23, 2026 · 11.6K Views1 Reply · 5 Reposts · 9 Likes
Can prediction markets win over Wall Street? (The Economist): “It was on Wall Street that Luana Lopes Lara, the 30-year-old co-founder of Kalshi, was inspired to start a prediction-markets exchange. As an intern at hedge funds such as Five Rings Capital and Citadel Securities, she was baffled to find fund managers building elaborate portfolios to take positions on forthcoming elections and interest-rate decisions. Kalshi’s users bet directly on events instead.”
“What we are building is a financial exchange where anyone from a Robin Hood trader to Goldman Sachs to someone in an mit dorm could trade directly in what their thesis was about the future,” Ms Lopes Lara says.
Prediction markets need better rules (The Economist): “Some call them “truth machines”. Prediction markets, in which punters can bet on anything from the outbreak of war to what celebrities will wear, reveal in their prices the closest thing to humanity’s best guesses about the future. Such markets can provide both entertainment and economic benefit. If people and firms can discern risks and opportunities from market prices, they will make better decisions. Some might even trade to hedge their exposure to events: one American bet big against the government forgiving his student debt, allowing him to pay some down whatever happened.”
Betting account in George Cottrell’s name received $9mn in crypto from unidentified sources (Financial Times, paywall): FT is pretty serious about its paywall so I won’t be able to share the interesting stuff here. But it’s interesting!
I used to ignore prediction markets. Then I learned people were betting on wildfires (High Country News): “My reporting convinced me that viewing wildfires as entertainment or for profit has dangerous consequences. Gamifying something deadly and profiting off an event that destroys communities does not sit right with me. I’ll be curious to see if the next megafire that captures national attention is open for wagers, or whether platforms, states or the federal government will eventually decide the risks aren’t worth the rewards.”


⏱️ Day 19 of asking for more than one CFTC commissioner
This is day 19 of me asking the Trump administration to appoint more commissioners and at least one Democrat:
