


Don’t lie: I know you already read all 267 pages of the Commodity Futures Trading Commission rules proposal for prediction markets that dropped on Wednesday.
(God help you if that’s true.)
In some ways, the proposed rules are a nothingburger. They mostly codify the status quo as we have all come to understand it and attempt to justify the massive expansion of the prediction markets industry. It’s very industry friendly.
It’s also arguably a really big deal, because it clarifies rules that were not terribly clear and sets us down a path to future-proof how prediction markets are handled.
“The CFTC will protect the integrity of our regulated markets without standing in the way of responsible innovation,” CFTC Chairman Michael Selig said in a press release. “This proposal gives the Commission a durable, transparent framework to identify the contracts Congress directed us to scrutinize while letting legitimate markets move forward.”
Here are five things you should know about the proposed rules:
1. Sports events are mostly fine at prediction markets, with some exceptions
We already knew this would be the case, right? The current posture (before the rules proposal) is that pretty much all sports events are events that can be traded. Some people seemed to be holding out hope that player props (bets/trades on player statistics) and parlays (SORRY, COMBOS) would not be allowed. The CFTC to those people:
The CFTC appears to view pretty much everything currently going on at prediction markets on sports events as kosher:
“The Commission observes that prediction markets have successfully listed for trading a wide variety of event contracts based on sports activities. The Commission preliminarily finds that certain characteristics of event contracts involving sports activities would reduce the basis for finding that the event contracts are contrary to the public interest. For example, the extent to which event contracts settle based on the overall outcome of a sporting event – including final scores, point differentials, win-loss results, tournament advancement, individual or team statistical performance or season long performance metrics—would be factors against a finding that the event contracts are contrary to the public interest. The Commission preliminarily believes that these categories of sports event contract markets may serve price discovery functions and provide meaningful information.”
So there you go: That’s pretty clear! Player props have not become that big at Kalshi and prediction markets in general… yet. But this gives a pretty clear green light to player-stat markets via “individual … statistical performance.” The proposal does not take direct aim at combos as a category, either.
What may be found “contrary to the public interest” if a prediction market tried to list a sports event contract because of concerns about manipulation, insider trading, etc? From the proposed rules:
“Player injury contracts. The Commission preliminarily believes that event
contracts that explicitly settle solely by reference to the duration, severity, occurrence, or medical diagnosis of an injury sustained by a specific athlete raise serious public interest concerns.”
🔍 Some versions of injury markets had been listed previously, but looks like we may not see them again.
“Officiating outcome contracts. The Commission preliminarily believes that event contracts that settle solely by reference to judgment calls, discretionary decisions, or rulings of referees, umpires, or other game officials, including without limitation, penalties assessed, fouls called or not called, reviews initiated, video replay decisions, player ejections, or disciplinary rulings made during live games raise public interest concerns.”
“Discrete-action contracts involving specific participants. The Commission preliminarily believes that event contracts that settle solely by reference to a discrete action, event, or occurrence in sporting events, including, without limitation, event contracts settling on the type of a specific play called for or executed by a specific player or team, the type or outcome of a specific pitch thrown by a specific pitcher, the outcome of a specific shot taken by a specific player, or whether a specific player or team commits a specific foul or penalty, present public interest concerns.”
🔍 This is probably the most interesting, as it wasn’t clear that they wouldn’t be allowed. Sportsbooks do offer these to some extent now. It’s not clear how good of a fit these would be at prediction markets anyway, but now it looks like we won’t have to worry about it.
“Physical altercation contracts. The Commission preliminarily believes that event contracts that settle solely by reference to physical altercations, fights, or conduct between players or participants in the game that are subject to penalty, ejection, or disciplinary action raise public interest concerns.”
“Pre-collegiate sports events. The Commission preliminarily believes that event
contracts that settle solely by reference to games, sporting events, or outcomes in which participants are below the collegiate level raise public interest concerns.”
🔍 It’s good to see no betting on youth sports here. Offshore sportsbooks sometimes do book action on high school games and the Little League World Series. But there’s really no place for betting on these things.
To be clear, none of these are banned out of hand, but it seems the CFTC is basically saying “don’t go there.”
2. ‘Gaming’ doesn’t = the act of gambling
First off, here’s how the CFTC describes the existing Rule 40.11(a)(l) says:
“…that a registered entity shall not list for trading or accept for clearing on or through the registered entity an agreement, contract, transaction, or swap based upon “an excluded commodity, as defined in Section 1a(19)(iv) of the Act, that involves, relates to, or references terrorism, assassination, war, gaming, or an activity that is unlawful under any State or Federal law.”
Did you think “gaming” under CFTC rules meant gambling on sports? Again:
The CFTC made it clear that’s not what it thinks now:
Proposed § 40.11(b) sets out the following definition: “Gaming means any activity that: (i) one or more participants typically engage in for purposes of recreation or to entertain others, (ii) is governed by rules; and (iii) includes measurable occurrences or outcomes that depend on the participants’ luck, skill, or athletic ability during the activity.”
And later:
The Commission also notes that if an activity is not gaming as defined above, the mere fact that gambling occurs in relation to that activity does not make it gaming.
I don’t think I have ever seen “gaming” defined quite in this way — the common usages are for video gaming and gambling. But I digress.
3. Event contracts on casino games are (probably?) out
Roulette spins are an event, right? But apparently you won’t be able to trade on them:
For these reasons, the Commission preliminarily believes it would be more likely to find that the event contracts involving an Enumerated Activity are contrary to the public interest where the event contracts lack the potential to inform any economic, commercial or financial decisions. This includes event contracts that settle based on purely random events, such as the spin of a roulette wheel or the outcome of a random-number generator.
Interestingly, the rules talk about poker as a game “of mixed chance and skill.” Lots of casino games have some skill involved…like if you randomly hit or stood on every hand of blackjack you would do terribly. But if you follow optimal strategy you will at least reduce the house edge.
And again, like the sports stuff above, nothing is just “banned.” The CFTC is saying it probably wouldn’t allow it because of the “contrary to the public interest” standard.
4. The proposal spends a lot of time justifying things
That’s on purpose, of course. Selig wants these rules to stay after he is gone, and he is trying his best to make them be able to stand up to any future legal challenges. Whether he succeeds is an open question.
Particularly interesting is the section talking about the record on the Dodd-Frank Act, which is how all this started. I and others often point to a discussion on the Senate floor as evidence Congress didn’t intend to allow sports betting via prediction markets. The CFTC pushes back on that (emphasis added by me):
The Special Rule was added to the CEA by section 745(b) of the Dodd-Frank Act, which amended the requirements for contract and rule submission by adopting a new version of CEA section 5c(c). The only discussion of the Special Rule in the legislative history of the Dodd-Frank Act is a short colloquy on the Senate floor between the late Senator Diane Feinstein and Senator Blanche Lincoln, then-Chair of the Senate Committee on Agriculture, Nutrition, and Forestry. In this colloquy, the two Senators appear to be talking about two different types of derivatives contracts, and Senator Lincoln (the author of the Special Rule) never expressly adopts Senator Feinstein’s reasoning. …
Senator Feinstein describes a broad swath of speculative derivatives, saying, “[s]ince 2000, derivatives traders have bet billions of dollars on derivatives contracts that served no commercial purpose at all and often threaten the public interest,” before expressing that the Special Rule should authorize the CFTC to “determine that a contract is a gaming contract if the predominant use of the contract is speculative as opposed to a hedging or economic use.” The Commission preliminarily believes that Senator Feinstein is suggesting that the activity of “gaming” in the Special Rule would encompass “billions of dollars” of contracts—i.e., the derivative contracts that she believes contributed to the 2008 crisis.
Senator Lincoln, on the other hand, says the purpose of the Special Rule is “to prevent the creation of futures and swaps markets that would allow citizens to profit from devastating events and also prevent gambling through futures markets.”That is, in contrast to Senator Feinstein’s reference to past contracts, Senator Lincoln looked at types of event contracts that could potentially be developed in the future.
The Commission preliminarily believes that the colloquy between Senators Feinstein and Lincoln does not indicate an intent to revive the public interest/economic purpose test that applied before the CFMA. The “billions of dollars on derivatives contracts that served no commercial purpose at all and often threaten the public interest” to which Senator Feinstein refers would not be subject to the Special Rule, and arguably would not be prohibited under the pre-CFMA test. And Congress was aware of the history surrounding the economic purpose test but chose not to incorporate it into the text of the Special Rule. In any case, the Commission notes that a floor colloquy is not a definitive source of Congressional intent. For these reasons, and in addition to the generally limited value of legislative history, the Commission preliminarily believes that the colloquy is of limited usefulness to understanding the purpose of the Special Rule. Thus, the Commission preliminarily believes that the Special Rule contemplates a new type of public interest test.
Senator Lincoln continued the colloquy by saying, “[t]he Commission needs the power to, and should, prevent derivatives contracts that are contrary to the public interest because they exist predominantly to enable gambling through supposed ‘event contracts.’ It would be quite easy to construct an ‘event contract’ around sporting events such as the Super Bowl, the Kentucky Derby, and Masters Golf Tournament. These types of contracts would not serve any real commercial purpose. Rather, they would be used solely for gambling.” Senators Feinstein and Lincoln then conclude the colloquy by saying that the Special Rule “will also” authorize the Commission to prevent trading in event contracts relating to national security events such as terrorism and war.
The Commission preliminarily believes that the colloquy between Senators Feinstein and Lincoln establishes that Congress was aware that event contracts based on “sporting events such as the Super Bowl, the Kentucky Derby, and Masters Golf Tournament” could potentially be submitted under CEA section 5c(c), but Congress chose not to prohibit event contracts involving those sorts of events. Instead, the Special Rule confirms the CFTC’s jurisdiction over event contracts and sets out a process by which the CFTC “may” find such event contracts to be contrary to the public interest. Notably, the statute does not authorize the Commission to impose a per se prohibition on the listing of such event contracts independent of a public interest determination.
The Commission has carefully considered the floor statement of Senator Lincoln, expressing concern that event contracts on sporting events might “not serve any real commercial purpose” and “would be used solely for gambling.” The Commission preliminarily shares the underlying concern that the Special Rule should prevent the use of prediction markets as venues for event contracts that have neither commercial utility nor informational value. This proposal’s framework operationalizes that concern through contract-specific application of the public interest factors set forth in proposed § 40.11(a)(5) and (a)(6), rather than through a categorical prohibition based on the identity of the underlying event. Former Senator Lincoln’s own comment in response to the Commission’s Advance Notice of Proposed Rulemaking on Prediction Markets supports the appropriateness of this approach. Senator Lincoln explained that “[s]ome contracts genuinely should be prohibited—direct references to specific acts of terrorism, named-individual assassinations, military operations,” while “[o]ther contracts that help users manage real economic exposure should not be prohibited.” Senator Lincoln specifically identified “the Super Bowl” as an example of a sporting event with “strong commercial value” because of its “major impacts on advertising, apparel sales and the hospitality industry.” The framework proposed herein reflects these considerations.
That’s a lot of words just on that topic! I’d say much of this is a strained retelling/reading of what happened. But again, I digress.
5. Prediction markets are encouraged to work with leagues
There are no rules saying that prediction markets have to listen to leagues or do what they say. However, it seems to incentivize these relationships:
“As noted above, event contracts involving sports may implicate the involvement of a recognized governing body, integrity unit or comparable monitoring function for that sport, including but not limited to professional sports leagues and their integrity units, as well as the National Collegiate Athletic Association. The Commission preliminarily believes that communication between prediction markets and such relevant governing bodies or authorities prior to listing sports event contracts would support compliance and surveillance programs for sports events contracts. The Commission also preliminarily believes that establishing formal information sharing agreements between prediction markets, the Commission, and the relevant sports integrity monitoring organization may aid prediction markets in monitoring sports event contracts for manipulation, insider trading and other compliance issues. Such engagement and information sharing efforts could entail a practice or agreement with the relevant sports governing body that the prediction market will:
Report suspicious trading activity or trading activity by prohibited traders to the relevant sports governing body;
Cooperate with sports governing bodies to provide certain data in connection with sports integrity investigations;
Consult with sports governing bodies on proposed event contracts; and
Consult, as appropriate, with relevant governing bodies regarding integrity-related restrictions applicable to marketing, participant protections, and event contract design in the relevant sport.
To the extent a prediction market coordinated with or entered into information sharing arrangements with the relevant sports leagues or governing bodies and/or designs event contracts in accordance with league integrity standards, where applicable, those facts would weigh against a finding that the applicable event contracts are contrary to the public interest.
For these reasons, the Commission preliminarily believes that event contracts based on the aggregate outcomes of professional or collegiate sports events, based on objective and verifiable settlement criteria, listed by prediction markets that maintain appropriate surveillance, trading prohibitions, and coordination with relevant sports governing bodies, are, depending on the full record and the Commission’s evaluation of all relevant factors, unlikely to be found to be contrary to the public interest.”
If you glossed over all of that or don’t want to read it, the CFTC is basically saying: “If you play nice with the leagues, use their data, and don’t piss them off, your sports event contracts are probably fine.”
But leagues don’t get full veto power over what can and can’t be listed, it appears.
More on the proposed rules
Press release from the CFTC here. Whole thing below.

The CFTC will take comments for 45 days after publication, and the rule could be amended after that.
Other takes/reporting on the rules:
Sportico | CFTC Posts Prediction Market Rules: What It Means for Sports: “But the CFTC does not set any concrete boundaries on how exchanges advertise their offerings, nor does it specifically address so-called mention markets in which people can bet on what public figures will say during media appearances such as broadcasts or postgame press conferences. The CFTC also does not heed calls for prediction market platforms to change their minimum age requirement from 18 to 21. Most state-regulated gambling companies do not take bets from people under 21.”
Front Office Sports | CFTC’s Proposed Sports Rules Won’t Quiet Prediction-Market Critics: “The CFTC is doubling down on the idea that they think sports are an area that falls within their jurisdiction,” former CFTC lawyer Carl Kennedy, who now works at law firm Katten Muchin, tells Front Office Sports.
Axios | 1 big thing: Game (almost) on: “The CFTC today moved to formalize rules allowing prediction markets to offer the equivalent of sports betting nationwide — with some specific types of trades disallowed.”
Covers points out…:
 Geoff Zochodne@GeoffZochodneThe "if we don't offer it the black market will" argument makes an appearance in today's proposed rulemaking by the CFTC as well. Could rejig this graf just a little bit and a sportsbook operator could use it to argue for college player prop betting in any given state.
 4:47 PM · Jun 10, 2026 · 701 Views1 Reply · 1 Repost · 4 Likes
Straight to the Point:
Rep. Dina Titus:
 Dina Titus@repdinatitusThe @CFTC’s proposed rule reinforces its failure to respect state and tribal sovereignty. Arguing that sports event contracts are anything but sports betting is pure fiction. Rather than confronting that reality, the agency appears more interested in cozying up to @POTUS’s family6:47 PM · Jun 11, 2026 · 1.62K Views7 Replies · 1 Repost · 9 Likes


You can’t pause current events when your payments can’t keep up. With every failed deposit or lengthy withdrawal process, customers lose trust in your brand. And when money doesn’t move fast enough, your liquidity suffers. PayNearMe’s PayXMTMplatform is purpose-built for Payment Experience Management, giving you the fast, familiar payment options your customers want while streamlining back-end operations for your team. Get real-time payments for real-time events—from one simple integration.
📊 The Ticker
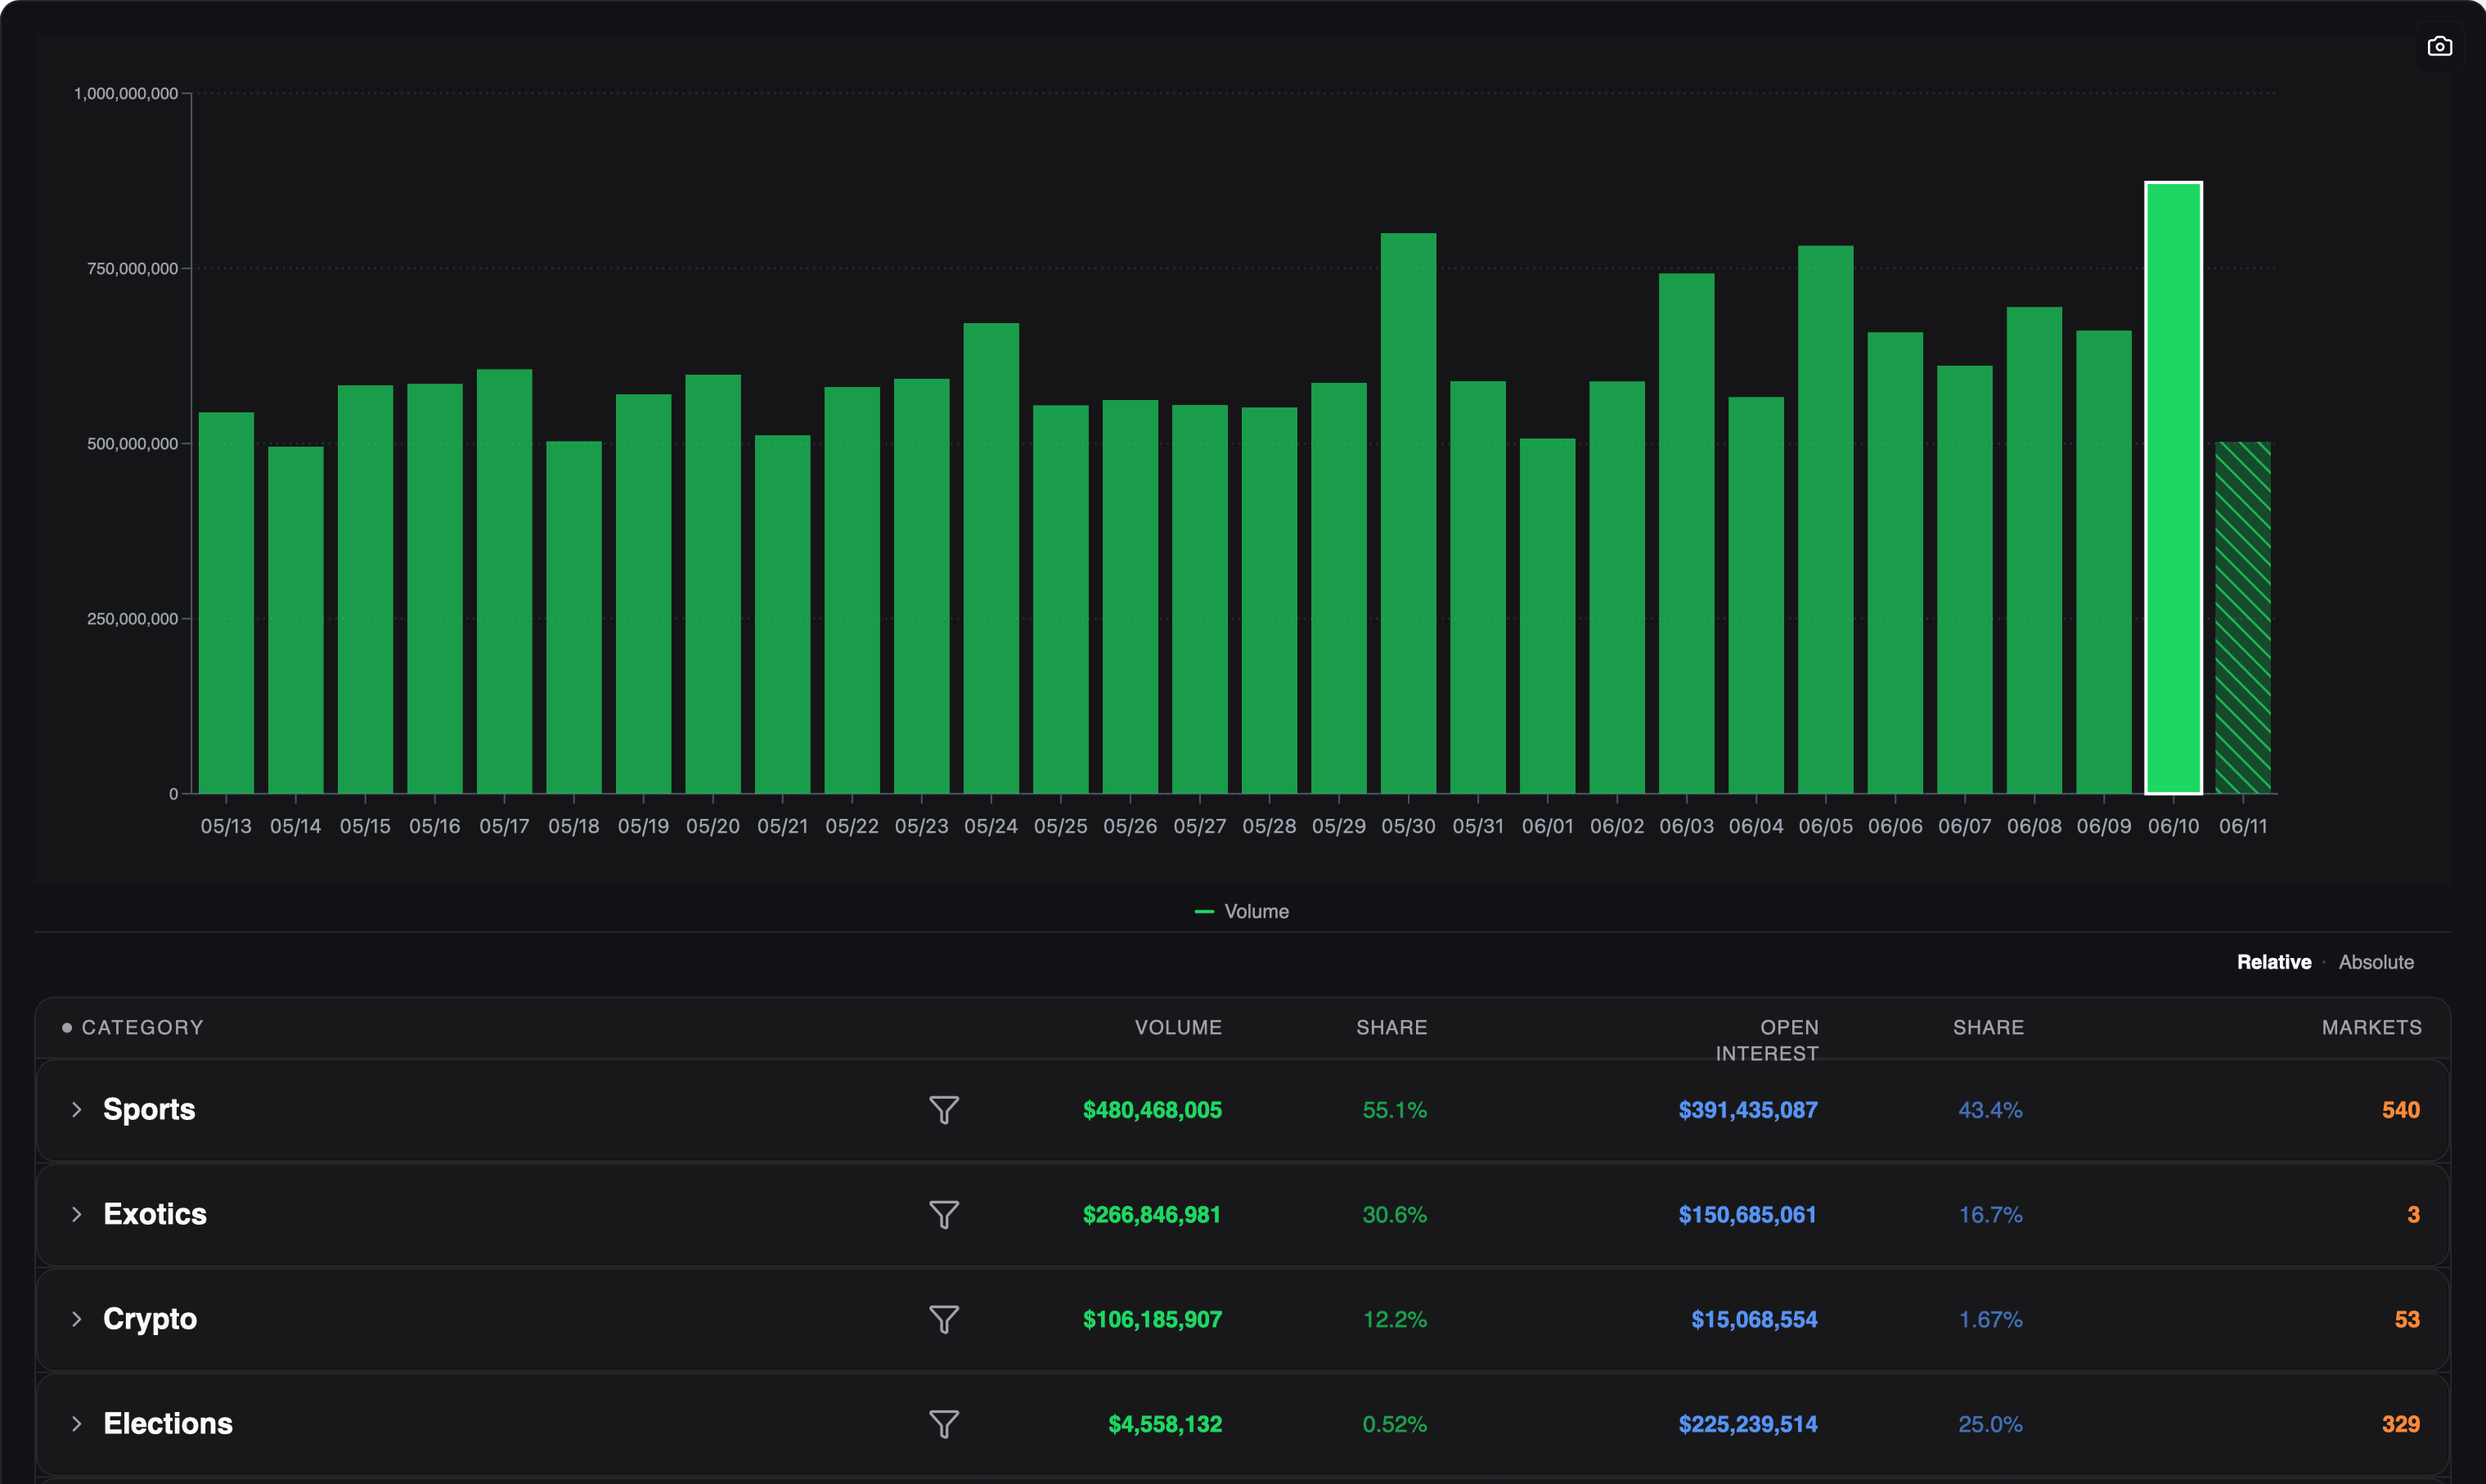
Kalshi posted a new daily record for volume on Wednesday, beating the day of the Super Bowl by about a million dollars:
Volume: $872.2 million
Sports + parlays: 85.7% of volume
Crypto markets: 12.2% of volume
More than 30% of total volume came from parlays.
Trend line and breakdown of Wednesday from Ticker Tracker:
Prediction markets news roundup
🚨 The important stuff
ProphetX Obtains CFTC Approval to Operate America's First Federally Regulated Sports-Native Exchange (press release): ProphetX, America’s first sports-native prediction market, today announced that the U.S. Commodity Futures Trading Commission (CFTC) has approved its applications to register as a Designated Contract Market (DCM) and a Derivatives Clearing Organization (DCO). With these CFTC licenses, ProphetX is poised to become the first sports-native, direct-clearing prediction market to launch and operate in full compliance with the CFTC’s DCM and DCO regulatory framework. The approvals follow Prophet’s submission of its DCM and DCO applications in November 2025, as well as its April 2026 comment letter responding to the Commission’s Advance Notice of Proposed Rulemaking on Prediction Markets.
“This approval positions ProphetX to become the first sports-native direct-clearing prediction market in the United States,” said ProphetX CEO and Co-Founder Dean Sisun. “We can now expand our best-in-class sports event market offerings to millions of Americans across the country while competing on a level regulatory playing field. ProphetX thanks CFTC Chairman Selig for his leadership and the Commission’s staff for their work throughout the application process, and we look forward to helping shape the future of prediction markets.”
By obtaining dual registration as a DCM and DCO, ProphetX intends to operate a vertically integrated marketplace that allows users to directly trade, clear, and settle event-based contracts under comprehensive CFTC oversight.
ProphetX’s regulated market structure includes a proprietary Request for Quote (RFQ) Parlay Mechanism, which enables users to construct and price multi-event combinations directly with counterparties. The mechanism mirrors institutional trading protocols used in traditional financial markets, delivering flexibility, transparency and competitive pricing to event-based contracts.
ProphetX’s eight-year regulatory journey began in the United Kingdom in 2018, where it was licensed as a peer-to-peer marketplace for sports event trading. The company was building exchange infrastructure for sports-based contracts years before U.S. prediction markets entered the sports event contract space. Today’s CFTC approval positions ProphetX to further advance its market-leading platform, drive innovation, and expand its presence in the rapidly growing prediction markets industry.
Commission of 1: A top Wall Street regulator gains new sway over crypto, prediction markets under Trump (Politico): “Michael Selig, who leads a tiny Wall Street regulator, in less than six months on the job has begun ushering in a friendlier landscape for the hottest and riskiest frontiers of finance. But his ascendance is drawing alarms on Capitol Hill and even within his own agency, the Commodity Futures Trading Commission.”
Kalshi’s Push To Punish Polymarket Has Yet To Move CFTC (Sportico): “In a letter to the CFTC dated April 30 regarding prediction market rulemaking, Lopes Lara asked Selig to crack down on Kalshi’s main competitor Polymarket for not doing enough to block U.S. citizens from accessing its unregistered international exchange. The CFTC’s much-anticipated rule proposal for exchange betting, released on Wednesday, makes no mention of that issue. It remains possible the CFTC will take on Polymarket separate from this round of rulemaking, but the agency has not indicated any plan to do so.
Timothée Chalamet + Kalshi:
Timothée Chalamet Gets Into Kalshi Promo in the Most Timothée Chalamet Way (GQ): “The spots are incredibly random, and decidedly indirect with regards to what they’re marketing, which is the point, of course—in keeping with the TC brand of being lightly weird and heavy on the meta. (Remember the Cash App commercial?) It’s an ad for one of the most rapidly expanding brands on the planet, but still manages to feel voyeuristic and just left-of-center enough to be charming. Now all we need is a “leaked” Zoom call of Tim pitching a bunch of Kalshi execs on increasingly outlandish concepts.”
Timothée Chalamet Roasted for Kalshi Prediction Market Ad: ‘Bro Sold His Soul’ (The Wrap): Online reaction overwhelmingly did not support the actor’s latest endorsement. “Had to pay for those courtside seats somehow,” one user commented on his Instagram post, referencing how Chalamet has sat courtside at nearly every New York Knicks game of the NBA Finals.
⚖️ Legal and regulatory news
Vault: Are the odds in Kalshi’s favor? (Punchbowl): “Kalshi CEO Tarek Mansour knows that Congress has questions — some might say concerns — about the prediction market empire he’s building in the United States. Mansour and his company have embraced the challenge.”
“Why should we expect every person in Congress to know what these things are?” Mansour told us in an interview Wednesday afternoon, referring to prediction markets. “They’ve become a thing in the last six months. I mean, they have a million other things to worry about.”
Crow on prediction markets, Iran war and more (Punchbowl): “Rep. Jason Crow (D-Colo.) told us on Fly Out Day today that he wants to ban all members of Congress from using prediction markets like Kalshi and Polymarket. Crow, 47, said he wants to ‘get back to the point of Americans trusting institutions and trusting elected officials.’”
📣 Industry news
LIGA MX and Polymarket announce sponsorship agreement for the US territory with official data and integrity collaboration from Genius Sports (press release): LIGA MX, Polymarket and Genius Sports (NYSE:GENI) today announced a new agreement that will see Polymarket, the world’s largest prediction market, become an official sponsor of LIGA MX in the US territory, with Genius Sports providing official data and integrity information-sharing services underpinning the partnership.
Under the agreement, Polymarket will serve as the official and exclusive prediction market partner of LIGA MX in the United States, spanning league competitions including Campeón de Campeones, the annual match between the champions of the Liga MX Apertura and Clausura tournaments, scheduled for July 25, 2026, in Carson, California.
Liga MX’s Official Data, Streaming and Integrity Partner, Genius Sports, will provide Polymarket with official sports data to support the creation and settlement of related sports prediction market contracts. …
“LIGA MX is one of the most exciting and widely followed football leagues in the world,” said Ari Borod, President of Sports Business Development at Polymarket. “Genius Sports’ official data and integrity infrastructure ensures every Liga MX market on Polymarket is built on the foundation of trust and transparency the league and its fans deserve.” …
Polymarket’s Liga MX markets will be available to eligible U.S. users beginning with the 2026-27 season, which kicks off in July 2026 and includes Campeón de Campeones on July 25, 2026, in Carson, California.
📖 Everything else you should know/read
Knicks Run Moves Kalshi, Polymarket Off the Timeline and Into the Streets (Front Office Sports): “Knicks fans have been taking to the New York City streets to celebrate the team’s success during this year’s NBA Finals run. At the same time, Kalshi and Polymarket are trying to capitalize on the momentum, turning the internet culture they cultivate into real-world, viral marketing moments.”
Kalshi Co-Founder: Prediction Markets Will Be Bigger Than the Stock Exchange, Even If You Lose Money (PC Mag): “A principal at one of the two best-known prediction markets backed up one of her bolder predictions in an appearance at Web Summit Rio: These outcome-wagering platforms will be bigger than the stock market. ‘I do stick by that,’ Kalshi co-founder and COO Luana Lopes Lara told Bloomberg News’ Tom Giles, senior executive editor of technology, in an onstage interview here Monday night.”
Prediction markets make America’s moral downfall a safe bet (The Hill): “Embraced by a president who sees prediction markets as the nation’s next big industry and abetted by cash-strapped states hungry to generate additional tax revenue, our elected leaders are hard at work turning America into the world’s largest casino floor. The result is a country where every government action has a potential profit incentive, every piece of information can be monetized, and our public officials are more interested in their prediction market profit/loss ratios than in basic questions of right and wrong.”
Former CFTC Chair Gary Gensler on regulating sports betting: Let the states do it (CNBC): Gary Gensler, former CFTC chairman under President Obama and former SEC chairman under President Biden, joins ‘Squawk Box’ to discuss why he’s filing an amicus brief arguing Congress did not intend to make the CFTC the nationwide regulator of sports betting when it passed the Dodd-Frank Act in 2010, regulating sports betting, his thoughts on prediction markets, insider trading concerns, and more.
DraftKings Stock Rallies On Prediction Markets Volume Report, Robins Comments (Legal Sports Report): “DraftKings shares extended their gains Wednesday after the company reported growing prediction market volume. Shares of DraftKings closed at $28.79, up 16.2% from Monday’s close before the company released its May volume report. That report, along with positive response from CEO Jason Robins on LinkedIn, helped send shares up 11.3% Tuesday.”
“Robins also appeared at the Nasdaq Investor Conference with Jefferies on Wednesday, before the market opened. The roughly 30-minute discussion focused largely on prediction markets, though Robins hit familiar talkings points regarding long-term growth opportunities in both sports betting and online casino as well.”
Susquehanna Takes Biggest Sports Loss, Kalshi Volume Hits Record High, On Knicks’ Game 4 Comeback (InGame): “Susquehanna International Group’s prediction market desk took its biggest ever sports loss making markets during the Knicks’ Game 4 NBA Finals comeback Wednesday, while Kalshi reported a record day for volume. Susquehanna’s losses, a source familiar with the situation says, were almost entirely on the game-winner market. …”
“I won’t confirm the exact loss, but it was a tough day,” Susquehanna co-founder Jeff Yass told InGame via the company’s prediction market team. “I grew up a Knicks fan but at this size, I was conflicted.”
SBC Summit Americas Day 2 live coverage: Prediction markets chat and First Pitch winner: “On a panel called ‘Prediction Markets: How Sportsbooks are Entering the World of Event Contracts‘, hosted by constantly newslettering consultant Dustin Gouker, panelists including Sporttrade Chief Operating Officer David Huffman, EdgeMarkets Founder and CEO Seni Thomas, 365Prediction Founder and CEO Dr. Laila Mintas, and MediaTroopers CEO Sam Segal assessed how sportsbooks such as DraftKings, Fanatics, and FanDuel are hedging their bets by stepping into the world of sports event contracts in states where they cannot offer state-regulated sports betting.”
 Patrick Everson@PatrickE_VegasExcellent discussion at @sbc_americas Prediction Markets Forum. @davidhuffman24 (@sporttrade_app) talking sportsbooks and the world of event contracts. Joined by EdgeMarkets’ Seni Thomas, 365 Predictions’ Laila Mintas and MediaTroopers’ Sam Segal. And @DustinGouker as your
 5:07 PM · Jun 11, 2026 · 2.6K Views1 Reply · 1 Repost · 2 Likes
